
Housing’s Regional Reversal Is a Supply Story
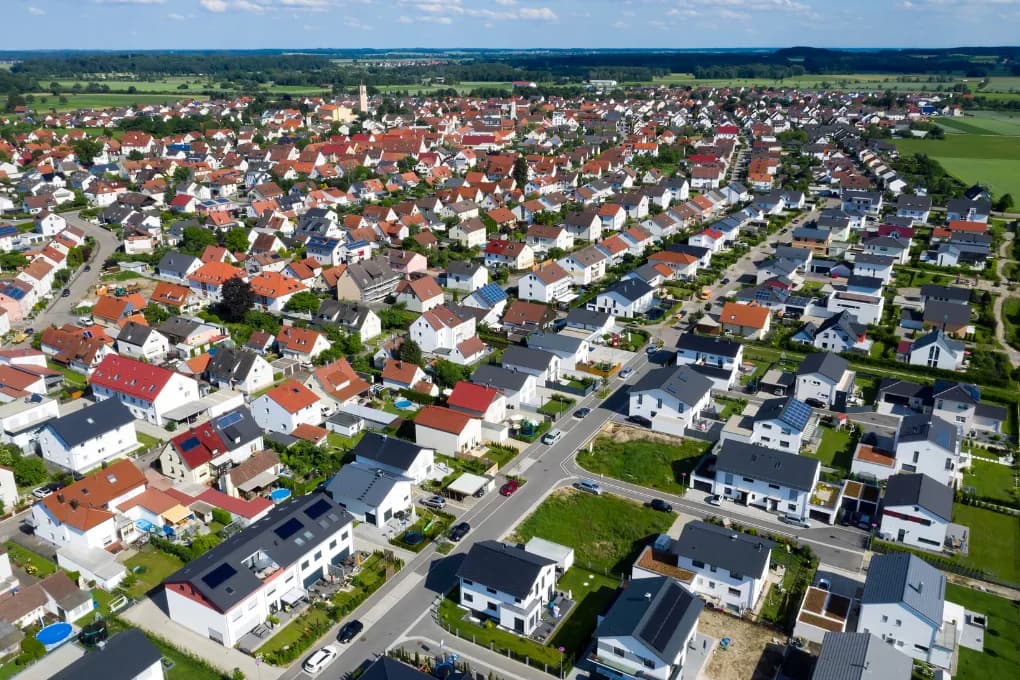
During the height of the pandemic housing boom, the story seemed straightforward. Homes in the Sunbelt were flying off the shelf. Domestic migration poured into Florida, Texas, and the Carolinas. Inventory disappeared almost overnight as buyers chased space, affordability, and lifestyle changes.
Meanwhile, much of the Northeast and Midwest was written off as stagnant. Slower population growth, colder climates, and older housing stock led many to assume these markets would continue to lag.
Today, that narrative has flipped.
In parts of the Sunbelt, days on market have extended, and inventory has climbed. At the same time, several Northeast and Midwest markets are facing tight supply and surprisingly resilient home price growth.
So what changed? The short answer is not migration. It’s supply.
The Sunbelt Responded to the Boom
In 2020 and 2021, record-low interest rates combined with extraordinary domestic migration created intense demand in Sunbelt markets. Builders responded as you would expect in pro-growth states with fewer regulatory barriers: they built.
Texas, Florida, and other high-growth markets saw significant new construction activity. Developers moved quickly to meet what appeared to be durable demand driven by relocation, remote work, and relative affordability.
Then conditions shifted.
By 2022, interest rates rose sharply. Affordability tightened. Demand cooled. Migration flows remained positive in many Sunbelt markets, but the pace slowed meaningfully from pandemic highs. Supply, however, had already expanded.
As new inventory continued to hit the market while demand normalized, balance returned. Days on market lengthened. Price growth moderated. In some metros, inventory began to accumulate. This is not necessarily a sign of structural weakness. It is the natural outcome of an aggressive building response meeting a slower demand environment.
The Sunbelt did not collapse. It adjusted.
The Northeast and Midwest Never Ramped Up
Now consider the opposite dynamic. Many Northeast and Midwest markets did not experience a comparable surge in new construction during the pandemic. Builders in places like parts of upstate New York, Ohio, and Pennsylvania did not dramatically expand supply.
When rates rose and demand cooled nationally, these markets were not carrying excess inventory. They simply had less to sell. In supply-constrained environments, even modest demand can keep inventory tight and pricing relatively stable. Without a wave of new homes entering the market, there is no supply overhang to absorb.
This helps explain why some colder, slower-growing markets are showing stronger relative resilience than high-growth Sunbelt metros.
The difference is not popularity. It is housing stock.
Migration Has Normalized, Not Reversed
Domestic migration has not stopped. Many Sunbelt markets remain net-positive migration destinations. Texas and Florida still offer relative affordability and economic opportunity compared to higher-cost coastal states.
But the pandemic surge was extraordinary. What we are seeing now is normalization.
When migration slows from exceptional to merely positive, and that slowdown coincides with elevated building activity, conditions soften. Meanwhile, markets that never expanded supply significantly never face the same inventory pressure.
Again, the throughline is supply.
Builders Still Hold an Advantage
Despite moderation in some markets, the new home sector remains a relatively bright spot. Builders are currently focused on selling existing inventory before breaking ground on additional homes, reflected in slowing permits and starts. But they retain a meaningful competitive advantage: flexibility.
Unlike individual homeowners, builders can offer mortgage rate buydowns and other financial incentives to attract buyers. In a higher-rate environment, that pricing power and incentive flexibility provide an edge over the existing home market.
What This Means for Investors
For investors, the lesson is straightforward. Regional performance is increasingly driven by supply dynamics, not broad migration headlines.
Markets that built aggressively are working through that inventory. Markets that constrained supply are showing resilience. The next phase of the cycle will reward local analysis over national narratives.
It is no longer sufficient to categorize markets as “hot Sunbelt” or “slow Northeast.” The more important questions are: How much was built? How quickly is inventory being absorbed? And how constrained is future supply?
In this environment, understanding the balance between construction and demand may be more valuable than tracking migration trends alone. The markets that surged first are normalizing. The markets that never expanded supply are holding firm.
If today’s housing divide is fundamentally a supply story, then thoughtful development becomes part of the opportunity. Dominion Financial’s Ground-Up Construction financing is structured to help experienced investors add inventory in markets where demand continues to outpace supply.
Frequently Asked Questions
Why are housing markets in the Midwest and Northeast outperforming some Sunbelt markets right now?
Why has inventory increased in some Sunbelt housing markets since 2022?
How does housing supply affect regional real estate market performance?
Has migration to Sunbelt states like Texas and Florida reversed?
How should real estate investors evaluate regional housing markets today?
Related Posts
View all Market Insight →
Migration + Demographics: The Real Estate Thesis Supply Data Can't Replace
Migration and demographic trends determine the long-term demand floor for a real estate market, while supply and absorption data explain shorter-term cyclical price and vacancy swings within that market. According to U.S. Census Bureau estimates, 31 states had positive net domestic migration between July 2024 and June 2025, led by North Carolina (84,000+ net arrivals), Texas (67,300), South Carolina (66,600), and Tennessee (42,000+). Florida's net domestic migration dropped sharply to 22,517 in 2025, down from 310,892 in 2022, reflecting rising property taxes, insurance costs, and home prices eroding its pandemic-era affordability advantage. Meanwhile, the Midwest posted positive net domestic migration for the first time this decade. Investors should evaluate both migration trends and current supply/absorption conditions together, since a market can have strong migration and still be temporarily oversupplied, or weak migration and still be tight due to limited new construction.
October 19, 2026

Why "Normalized" Rates Don't Mean a Normal Housing Market
As of September 2026, the 10-year Treasury yield (near 4.9-5%) and 30-year mortgage rates (around 6.67-6.76%) have returned to ranges considered historically normal by pre-2010 standards. Despite this, U.S. existing-home sales remain historically weak, falling to a seasonally adjusted annual rate of 3.98 million in August 2026, with months' supply climbing to 4.9, the highest level in over a decade, according to the National Association of Realtors. The gap between "normal" rates and a still-frozen transaction market is driven primarily by the mortgage rate lock-in effect: homeowners who bought or refinanced at 2.5-3.5% during 2020-2021 face a strong financial disincentive to sell, since moving means giving up that rate for a new mortgage well above 6%. This lock-in effect unwinds gradually, driven by individual life events rather than rate changes, meaning transaction volume may stay subdued even if rates hold steady or ease modestly.
October 12, 2026

What the 2021-2022 Buying Spree Got Wrong (And Replacement Cost Would Have Caught)
Institutional real estate investors who bought heavily in 2021-2022 often underwrote deals using IRR models and compressed cap rates that assumed cheap refinancing and aggressive rent growth would continue indefinitely. When interest rates rose and rent growth slowed, those assumptions broke down, and many of the same buyers became net sellers. Replacement cost, the cost to build a comparable property today, would have flagged those deals as overpriced regardless of interest rate assumptions, since it depends only on current land and construction costs rather than forecasts. As of 2024, construction costs made up a record 64.4% of a new home's average sales price in the U.S., according to the National Association of Home Builders, making replacement cost an increasingly useful underwriting benchmark for investors in 2026.
October 5, 2026