
Zombie Foreclosures Are Creeping Up: Smart Investors Should Be Paying Attention
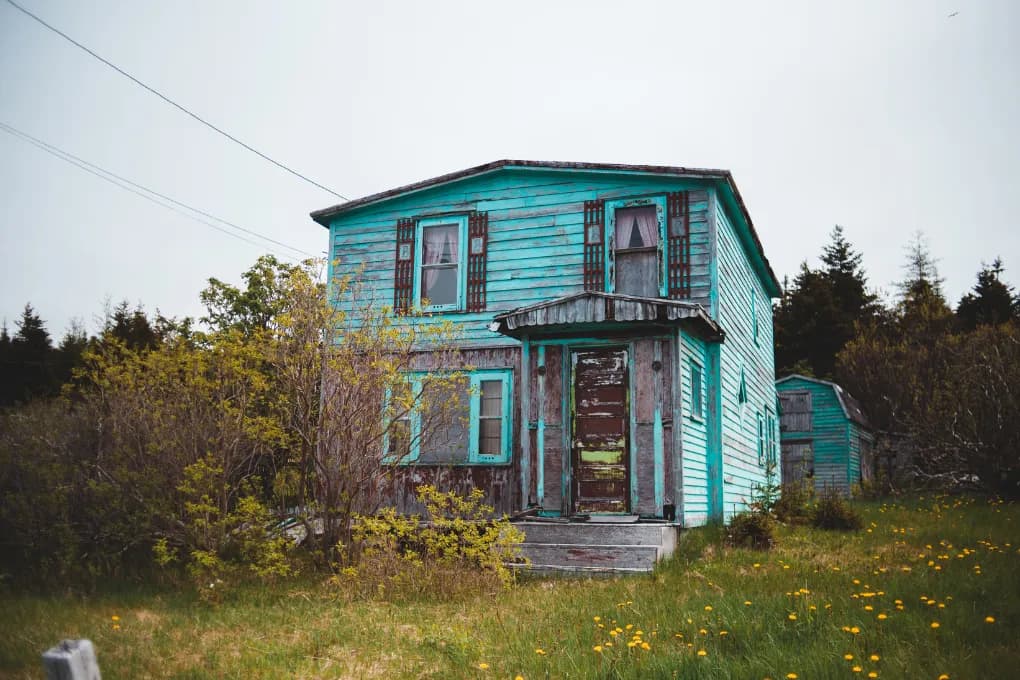
According to ATTOM, 7,519 zombie foreclosures are now scattered across the U.S., making up 3.38% of all pre-foreclosure homes. That’s up from 3.30% last quarter and 3.14% this time last year.
The uptick may sound modest, but in this market, even a small rise in distressed inventory can open big doors for real estate investors.
Zombie Homes, Explained
In real estate terms, a “zombie property” is a home caught in foreclosure limbo. The owner walked away. The bank hasn’t taken full possession. The grass grows tall, the mail piles up, and the property slowly decays into disrepair.
For neighborhoods, these homes can drag down property values and invite blight. But for fix & flip and buy & hold investors, they can be hidden gems – properties with built-in equity potential that traditional buyers overlook or avoid.
And right now, there are more of them, especially in investor-friendly states.
Where the Zombies Are Rising
Nationwide, 1.4 million homes (about 1.3% of U.S. housing stock) sit vacant. But not all vacant homes are equal. The sharpest spikes in zombie foreclosures year-over-year were found in states you might not expect, including some emerging investor hotbeds:
Colorado: +115%
Washington: +114%
Iowa: +84%
North Carolina: +80%
Oklahoma: +72%
Oklahoma, Kansas, Alabama, Missouri, and West Virginia all posted the highest overall vacancy rates this quarter, ranging from 2.1% to 2.4%.
For investors looking beyond the usual suspects, these trends suggest that secondary and tertiary markets could offer real upside – especially for value-add strategies or affordable housing redevelopment.
Midwest Metros: High Zombie Density = High Upside?
Among 135 metro areas analyzed by ATTOM, these five posted the highest zombie foreclosure rates: Wichita, KS (12.7%), Peoria, IL (12.3%), Youngstown, OH (10.1%), Cleveland, OH (9.5%), and Toledo, OH (8.8%).
In each of these markets, more than 1 in 10 homes in the foreclosure process are abandoned. This is a flashing green light for boots-on-the-ground investors ready to rehab and reposition.
Compare that to investor-saturated metros like Nashville, TN (0%) or Atlantic City, NJ (0.3%), and it’s clear where the path of least competition lies.
The Hidden Driver: Investor-Owned Vacancy
Across the U.S., 24.9 million properties are investor-owned, and 3.6% of them (roughly 882,000) are currently vacant. That’s not just a byproduct of market churn; it’s a signal that some portfolios are overextended.
Higher interest rates, inflation, and tighter cash flow have pushed some mom-and-pop landlords (and even mid-sized operators) to abandon unprofitable properties.
As inflation reshuffles portfolio priorities, the next 12 months could see a wave of off-market deals, portfolio liquidations, and distressed sales. Especially in legacy investor cities with aging housing stock and moderate appreciation.
What This Means for Investors Now
There’s no crystal ball, but the signs are hard to ignore:
Zombie foreclosures are ticking up.
Investor-owned vacancies are rising in key states.
High zombie density metros are concentrated in affordable, high-cash-flow regions.
For real estate investors, this isn’t a red flag – it’s a market signal.
Because while the headlines are still fixated on home prices, mortgage rates, and affordability crises, the smart capital is already sniffing out the next distressed inventory wave.
Why Dominion Financial Is Leaning In
If you’re ready to reposition neglected properties into performing assets, we’re ready to help you fund the mission.
Our lending platform is designed for speed, flexibility, and certainty:
Fix & Flip Loans: Up to 100% LTC, no appraisal, close in as little as 48 hours
Rental Loans: DSCR price-beat guarantee, fast closings
This is your early alert.
Start tracking high-vacancy metros, and line up your financing ahead of time – because when the next foreclosure ripple hits, speed will separate the opportunistic from the overwhelmed.
Frequently Asked Questions
What is a zombie foreclosure in real estate?
Why are zombie foreclosures increasing again?
How can investors profit from zombie properties?
What risks come with investing in zombie foreclosures?
How can investors prepare for rising zombie inventory?
Related Posts
View all Market Insight →
Migration + Demographics: The Real Estate Thesis Supply Data Can't Replace
Migration and demographic trends determine the long-term demand floor for a real estate market, while supply and absorption data explain shorter-term cyclical price and vacancy swings within that market. According to U.S. Census Bureau estimates, 31 states had positive net domestic migration between July 2024 and June 2025, led by North Carolina (84,000+ net arrivals), Texas (67,300), South Carolina (66,600), and Tennessee (42,000+). Florida's net domestic migration dropped sharply to 22,517 in 2025, down from 310,892 in 2022, reflecting rising property taxes, insurance costs, and home prices eroding its pandemic-era affordability advantage. Meanwhile, the Midwest posted positive net domestic migration for the first time this decade. Investors should evaluate both migration trends and current supply/absorption conditions together, since a market can have strong migration and still be temporarily oversupplied, or weak migration and still be tight due to limited new construction.
October 19, 2026

Why "Normalized" Rates Don't Mean a Normal Housing Market
As of September 2026, the 10-year Treasury yield (near 4.9-5%) and 30-year mortgage rates (around 6.67-6.76%) have returned to ranges considered historically normal by pre-2010 standards. Despite this, U.S. existing-home sales remain historically weak, falling to a seasonally adjusted annual rate of 3.98 million in August 2026, with months' supply climbing to 4.9, the highest level in over a decade, according to the National Association of Realtors. The gap between "normal" rates and a still-frozen transaction market is driven primarily by the mortgage rate lock-in effect: homeowners who bought or refinanced at 2.5-3.5% during 2020-2021 face a strong financial disincentive to sell, since moving means giving up that rate for a new mortgage well above 6%. This lock-in effect unwinds gradually, driven by individual life events rather than rate changes, meaning transaction volume may stay subdued even if rates hold steady or ease modestly.
October 12, 2026

What the 2021-2022 Buying Spree Got Wrong (And Replacement Cost Would Have Caught)
Institutional real estate investors who bought heavily in 2021-2022 often underwrote deals using IRR models and compressed cap rates that assumed cheap refinancing and aggressive rent growth would continue indefinitely. When interest rates rose and rent growth slowed, those assumptions broke down, and many of the same buyers became net sellers. Replacement cost, the cost to build a comparable property today, would have flagged those deals as overpriced regardless of interest rate assumptions, since it depends only on current land and construction costs rather than forecasts. As of 2024, construction costs made up a record 64.4% of a new home's average sales price in the U.S., according to the National Association of Home Builders, making replacement cost an increasingly useful underwriting benchmark for investors in 2026.
October 5, 2026