
The Rise of Manufactured Home Investing as a 2026 Strategy
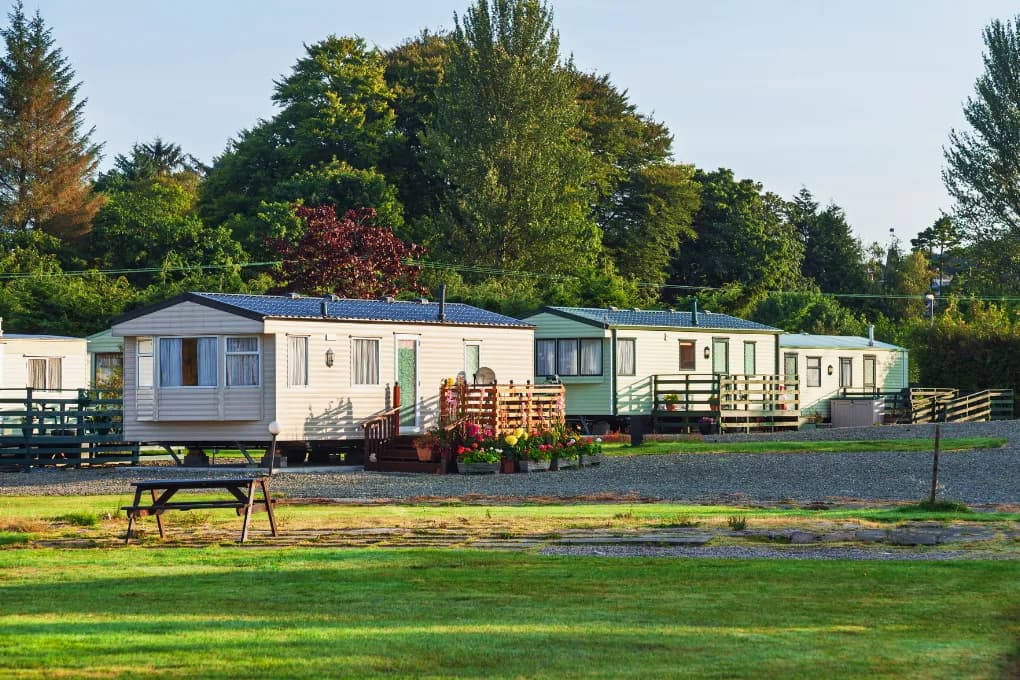
Manufactured home communities have long lived in the shadows of more mainstream asset classes. But in a market defined by affordability challenges, shifting demographics, and constrained housing supply, that’s starting to change.
More investors are taking a second look – not for speculative growth, but for consistent, defensible returns. As 2026 approaches, manufactured housing community (MHC) investing is earning a place in more sophisticated portfolios.
Manufactured Homes vs. Mobile Homes: What’s the Difference?
Though the terms are often used interchangeably, they refer to different things:
Mobile homes were built before June 15, 1976, when federal building standards did not exist.
Manufactured homes are HUD-regulated, factory-built homes constructed after June 15, 1976. They follow national codes for quality, safety, and energy efficiency.
Today, the vast majority of homes in manufactured housing communities are technically manufactured homes, not mobile homes. However, the term “mobile home park” is still commonly used when referring to the property type.
Supply Is Flat, But Demand Isn’t
Manufactured housing communities remain one of the most supply-constrained real estate asset classes. Barriers to entry are high due to zoning restrictions, land costs, and community resistance. While few new communities are being developed, manufactured housing production is climbing.
In 2024, U.S. factories shipped over 103,000 new manufactured homes, up more than 15% from the year prior, according to Construction Coverage. These homes increasingly serve working-class families priced out of traditional housing.
Meanwhile, the affordability gap in U.S. housing continues to widen. Over 20 million renters now spend more than 30% of their income on housing. Manufactured homes remain one of the last truly affordable options for working families.
As a result, well-located manufactured housing communities often see 90–95%+ occupancy and low turnover – even in slowing markets.
Sticky Tenancy, Predictable Returns
Unlike traditional multifamily housing, residents in manufactured housing communities often own their homes and rent only the land underneath. That structure brings several advantages for investors:
Lower ongoing maintenance costs for the operator
Reduced tenant turnover (relocating a home can cost $5,000+)
Less exposure to short-term rental volatility
That kind of predictability is attracting investors looking for yield in a high-rate environment.
Institutional Interest Is Growing
Ten years ago, manufactured housing communities were seen as a “mom-and-pop” niche. Today, institutional capital is entering, but selectively.
Large players like Blackstone have made headlines with major acquisitions. While institutional ownership still represents a small fraction of the market, their presence is helping validate the asset class.
Risks to Watch
No asset class is without risk. Investors should carefully evaluate:
Infrastructure quality – Older communities may require costly upgrades to utilities, roads, or septic systems.
Tenant profile – While tenant ownership promotes stability, under-managed communities may still face delinquency issues.
Regulatory environment – Certain states have enacted rent control or zoning rules that limit operational flexibility.
And like all real estate, manufactured housing communities are interest-rate sensitive. Valuations and cap rates have already shifted in response to recent hikes.
Why 2026 Could Be a Strategic Entry Point
After years of aggressive cap rate compression, the manufactured housing market is beginning to normalize. Buyer competition is easing, and sellers are adjusting expectations: creating more breathing room for experienced operators.
At the same time, demand fundamentals remain strong. For investors seeking reliable cash flow and downside protection, manufactured housing communities offer a middle ground between traditional rentals and commercial assets.
Final Takeaway
Manufactured housing community investing isn’t a trend; it’s a response to real, lasting demand. As affordability challenges persist and lower-cost housing becomes more essential, the fundamentals behind this asset class will continue to strengthen.
For investors focused on long-term durability, 2026 may be the right time to look more closely at manufactured housing.
Frequently Asked Questions
What is manufactured home investing?
How are manufactured homes different from mobile homes?
Why is demand for manufactured housing increasing?
What operational advantages do manufactured housing communities offer investors?
What risks should investors evaluate before buying a community?
Related Posts
View all Market Insight →
What the 2021-2022 Buying Spree Got Wrong (And Replacement Cost Would Have Caught)
Institutional real estate investors who bought heavily in 2021-2022 often underwrote deals using IRR models and compressed cap rates that assumed cheap refinancing and aggressive rent growth would continue indefinitely. When interest rates rose and rent growth slowed, those assumptions broke down, and many of the same buyers became net sellers. Replacement cost, the cost to build a comparable property today, would have flagged those deals as overpriced regardless of interest rate assumptions, since it depends only on current land and construction costs rather than forecasts. As of 2024, construction costs made up a record 64.4% of a new home's average sales price in the U.S., according to the National Association of Home Builders, making replacement cost an increasingly useful underwriting benchmark for investors in 2026.
October 5, 2026
The DSCR Dividend: How One Lending Product Changed the Game for Real Estate Investors and Communities
DSCR loans have reshaped real estate investing by giving investors a dependable refinance-to-rental exit. The DSCR Dividend examines data from Baltimore and markets nationwide to test whether DSCR lending encouraged more renovations, reduced the risk of challenging deals, and contributed to broader changes in vacant housing and homeownership.
September 29, 2026
The Fed Raised Rates for the First Time Since 2023. Here's What It Means for Your Next Deal
On September 16, 2026, the Federal Reserve raised the federal funds rate by 25 basis points to a target range of 3.75%-4.00%, its first hike since 2023, citing a strong economy and elevated inflation. Mortgage rates have already risen in response. For real estate investors, this means financing costs may stay elevated longer than expected, making speed, deal structure, and lender reliability more important. Dominion Financial offers DSCR rental and fix and flip loans with in-house underwriting designed to close quickly and deliver on quoted terms in shifting rate environments.
September 17, 2026