
The Power of Buying Below Replacement Cost and Economic Value
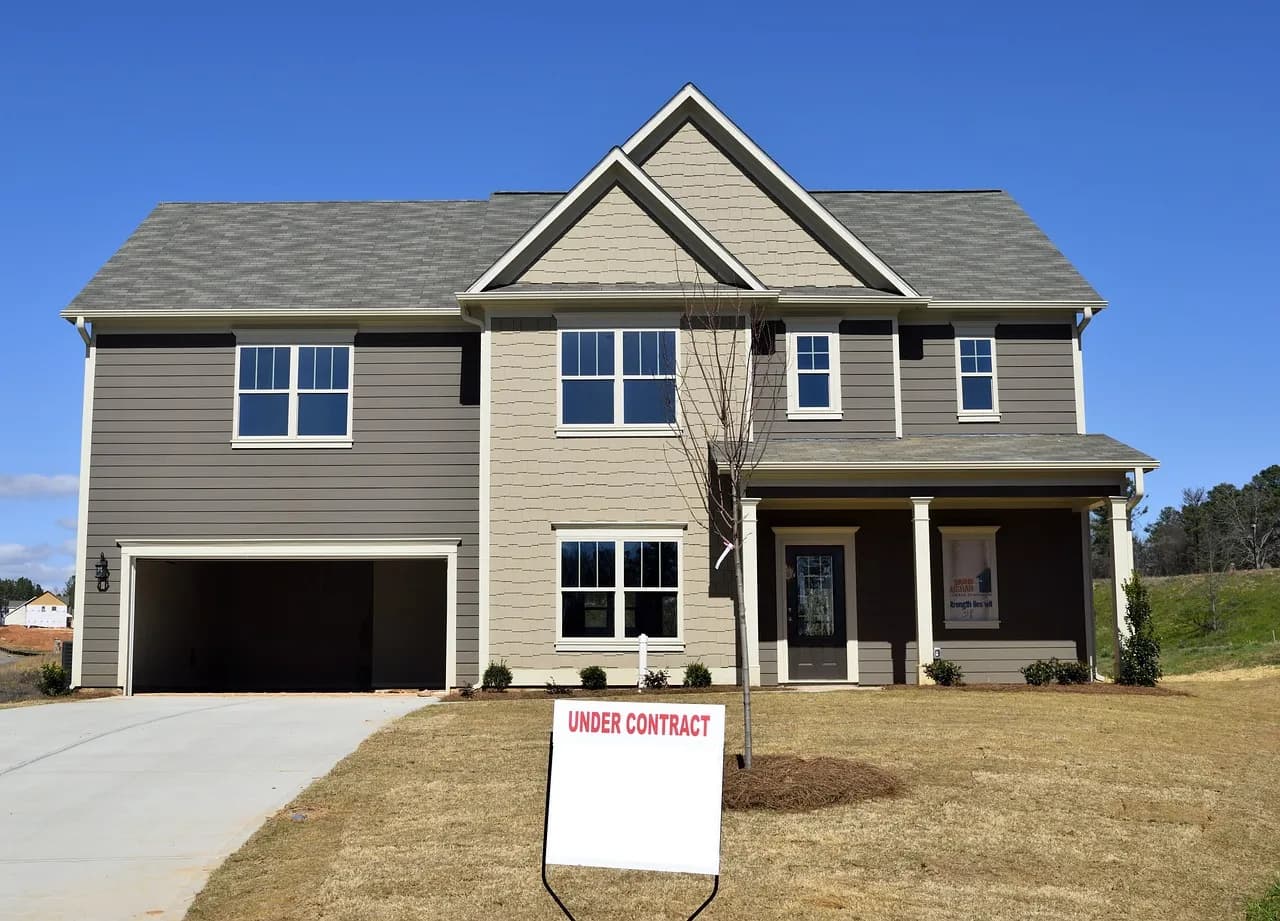
You may have heard that home ownership is less accessible today than ever before. While it’s true that home prices have soared in the past few years, that doesn’t mean real estate is no longer a smart investment. It all comes down to knowing the true value of your purchase.
The key to smart real estate investing is purchasing below replacement cost and economic value to maximize profitability. Here’s what you need to know.
Understanding Replacement Cost
Replacement cost is the cost it would take to fully replace an asset at current market rates. In real estate, that means replicating the property, construction, and land. Purchasing a home below replacement cost provides a financial safety net. There is less risk of losing your investment in an economic downturn.
For example, say you buy a property with a replacement cost of $300,000 for $250,000. That’s a $50,000 cushion in case property values drop before you can sell. This strategy puts you at an advantage for market corrections. It also leads to a higher potential ROI regardless of improvement costs.
Understanding Economic Value
The economic value of an asset is the amount a customer is willing to pay as opposed to its actual market value. In real estate terms, economic value refers to the cost comparison between renting and owning.
Here’s an example: In an area where the average rent is $2,000/month, homebuyers can afford roughly $250,000 in mortgage payments. A $200,000 home in that area is then considered below economic value.
Some common signs that a property is undervalued include:
Aesthetic damage but good structure
Seen as the “worst” option in a nice neighborhood
Highly motivated sellers
These properties have a stronger potential for appreciation than above-value homes in the same area.
Benefits of Buying Below Economic Value
A property listed below market value typically won’t stay that way. Market discrepancies tend to correct themselves over time. When prices are down, buying becomes more attractive than renting. This drives up demand and ultimately home values. On the flip side, high mortgage rates create higher demand for rentals, which eventually makes buying more advantageous.
That’s what makes a below-economic-value investment so profitable. Because the price isn’t overinflated at the time of purchase, it will always gain value over time as the market fluctuates.
Case Study: 2009 to 2017 Housing Market
The housing market from 2009-2017 is a prime example of this principle. In the wake of the recession, housing prices fell to an all-time low around 2011. This eventually made homeownership more financially viable to renters. By 2017, the market had become relatively stabilized.
An undervalued home purchased in 2006, before the market crash, would then be more resilient to fluctuations than an overvalued home. It would eventually regain its value over time. An undervalued home purchased in 2024, with prices at a record high, can expect similar resilience.
Final Thoughts
Understanding replacement cost and economic value is key to successful real estate investment. You should use these principles to help estimate the value of any potential investment before you buy.
If you’re looking for the right lender for your next property investment — whether you need a short-term bridge loan or long-term DSCR financing — check out Dominion Financial.
Related Posts
View all Investor Tip →
Why Tenant Screening Discipline Matters More in an Uncertain Economy
When rental demand is strong, and refinancing is easy, filling a vacancy quickly can start to matter more than screening rigorously. That tradeoff looks very different when rent delinquency rises. National rent delinquency reached 11.09% in May 2026, and late payments on independently owned rentals climbed from 8.8% in mid-2024 to 11.7% by June 2025. A single eviction now costs landlords an average of $6,767 in legal fees, lost rent, and turnover expenses. This piece covers why screening standards tend to loosen during high-demand years, what the current delinquency and eviction data show, and what landlords should be tracking now.
September 24, 2026
Using Public Data and AI to See Your Local Market More Clearly
Mainstream housing reports are aggregated and lagging by design, which limits how useful they are for understanding a specific neighborhood or block. Public records like permit filings, tax assessor rolls, water utility data, code violations, and business entity registries contain a much more granular picture, but they're scattered across different agencies and formats. AI is now being used to stitch these datasets together and surface patterns that would take a person weeks to find manually, from unregistered rental properties to hidden common ownership across multiple LLCs. This piece covers what data is available, how AI is being applied to it, and how investors can start building a clearer local picture.
September 24, 2026
Opportunity Zones Explained: What Changed and What It Means for Investors
The One Big Beautiful Bill Act made Qualified Opportunity Zones a permanent part of the tax code, replacing a program that was set to expire. New zone designations take effect January 1, 2027, under tighter eligibility criteria, and will be redesignated every 10 years going forward. Investments made after December 31, 2026, are subject to a new rolling 5-year deferral period instead of the old fixed 2026 recognition date, and continue to qualify for the standard 10% basis step-up at the five-year mark, while investments made before that deadline follow the original rules. Rural Opportunity Zones now carry a 30% basis step-up after a 5-year hold, versus 10% for standard zones, along with a reduced substantial improvement threshold, making rural deals notably more attractive than before. For investors, the practical impact is less urgency around a hard deadline and a new set of timing, location, and reporting considerations to weigh against other capital gains strategies.
August 27, 2026